A Milwaukee Couple Confronts Nearly $40,000 in Credit Card Debt
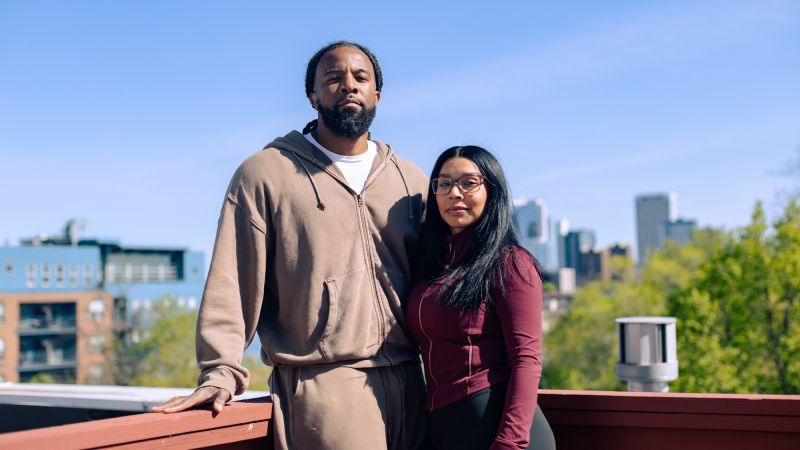
Sandego.net – Mariza and Geffrey Gordon are working to move beyond the paycheck-to-paycheck pattern that has shaped much of their financial life. For the Milwaukee couple, the most urgent challenge is almost $40,000 in credit card balances, much of it connected to their wedding last year.
The debt has made their monthly budget especially difficult to manage. They have been sending roughly $1,400 each month to cover required minimum payments, leaving less room for savings, unexpected costs and longer-term goals.
When the Gordons began receiving one-on-one financial guidance as part of a savings-focused program, their household situation changed quickly. They had enrolled while both were earning income, but Mariza soon learned that her job would be eliminated. Her severance package would last only two months, increasing the pressure to make careful choices.
Focusing on the Most Pressing Financial Problem
Financial educator and budgeting specialist Tiffany Aliche reviewed the couple’s circumstances and concluded that the available time would not be enough to solve every money concern at once. Instead, she chose to address the issue creating the greatest immediate strain: their revolving debt.
“The biggest thing weighing them down is their (credit card) debt,” Tiffany said.
She also noticed an important strength in the way the couple approached the situation. Rather than allowing financial stress to divide them, they were supporting each other and actively looking for help.
“They were so supportive of each other,” Tiffany said.
Aliche described the decision to seek guidance as one of their most positive steps, because financial problems can become harder to address when people feel overwhelmed and avoid confronting them.
“Seeking help. A lot of people just stay stuck,” she said.
High credit card balances can be difficult to reduce because minimum payments may keep an account current while allowing interest costs to continue. For a household already managing a job loss, identifying a realistic repayment approach can be as important as finding ways to cut spending.
Looking Beyond Debt Freedom
Before discussing spreadsheets, repayment options or credit scores, Aliche asked Mariza and Geffrey to picture what they wanted their lives to look like a decade from now. She calls the exercise “dreamscaping,” and its purpose is to give financial decisions a larger goal than simply escaping debt.
Her message was that eliminating balances is an important milestone, but it does not automatically create financial security. A person can have no debt and still lack savings, investments or a plan for building wealth.
“Let’s get to a point where you don’t feel like your debt is drowning you. But the true goal is to grow wealth,” Tiffany said.
The exercise resonated with the Gordons. They said they had been concentrating so intensely on their present financial stress that they had not spent much time discussing the future they hoped to build.
“We were so caught up in the now and stressed about the present we hadn’t put thought into what we want for the future,” Mariza said.
Their vision includes owning a home, eventually buying an investment property, taking occasional trips, launching businesses and establishing individual IRAs in addition to the retirement plans available through work. Those goals may take time, but putting them into words helped turn a debt-repayment discussion into a broader conversation about the life they want.
Exploring Repayment Alternatives
Along with developing a budget spreadsheet, Aliche encouraged the couple to investigate two possible ways to lower the burden of their card balances. One was to contact the National Foundation for Credit Counseling and ask about a debt repayment plan. The other was to see whether they could qualify for a personal loan with a lower interest rate or a balance-transfer credit card.
The counseling organization outlined a five-year repayment plan that would require monthly payments of $900. That figure is $500 below the amount the Gordons had been paying in credit card minimums. The lower payment could offer room in their budget, but the arrangement came with a significant restriction: they would be unable to use revolving credit during the five-year plan.
For now, the couple does not believe that solution fits their needs. With Mariza facing a layoff and the household seeking flexibility, they are hesitant to give up all access to revolving credit in case an emergency arises.
“Given our situation, we don’t feel that option is the best fit for us right now, as we want to maintain some flexibility in case we need access to credit,” they said in an email.
They also spoke with a credit union about alternatives. The outcome showed how closely repayment choices can be linked to credit scores: until their scores improve, they are not eligible for a personal loan at an attractive rate or for a balance-transfer card.
A balance-transfer card could be especially useful if it offered a promotional period with no interest, allowing more of each payment to go toward principal rather than finance charges. In the Gordons’ case, a qualifying card could provide as much as 21 months to repay transferred balances without interest. But that option is not currently available to them at favorable terms.
“We want to get our score high enough to get a balance transfer card,” Mariza said.
A Financial Reset in Progress
The Gordons’ next steps will involve balancing short-term needs with their longer-term plans. Their circumstances illustrate why a repayment strategy is rarely only about choosing the lowest monthly payment. A plan must also account for income uncertainty, access to emergency funds, borrowing costs and the practical ability to maintain the arrangement over time.
For Mariza and Geffrey, the immediate work is clear: understand their options, improve their credit standing and create a budget that supports both debt reduction and financial resilience. Their larger aim remains just as important—moving from a cycle of monthly stress toward a future with savings, ownership and greater choice.
Related Reading
Frequently Asked Questions
What is One couple wants to stop living?
One couple wants to stop living is the main topic of this guide. The article explains the context, practical details, and next steps readers should understand.
Why does One couple wants to stop living matter?
One couple wants to stop living matters because readers are looking for a useful answer, not just a short summary. Good content should match search intent and help them decide what to do next.